Noida, Uttar Pradesh, Sector 93B
Introduction
| Feature | Details |
|---|---|
| Project Name | Grand Omaxe (also listed on some portals/blocks as “Omaxe Grand,” “Omaxe Grand Woods,” or “Omaxe Grand Tower.” These appear to be sub-block/tower names within the same 22-tower complex, not separate projects; naming is inconsistent across aggregators) |
| Developer | Omaxe Buildhome Limited (CIN U70109DL2006PLC151613), a wholly owned subsidiary of the listed Omaxe Limited (CIN L74899HR1989PLC051918), a materially different fact from “built by Omaxe Limited” (see Builder Profile below) |
| Location | Block B, Sector 93B, Noida–Greater Noida Expressway, Gautam Buddh Nagar, Uttar Pradesh, PIN 201304 |
| Project Type | Residential apartments (group housing) |
| RERA Number | Not independently verified. Aggregators cite two conflicting numbers: UPRERAPRJ775 (NoBroker) and UPRERAAGT10119 (SquareYards, which carries the AGT prefix used for agent/channel-partner registrations, not project registrations), and neither resolves to a confirmed record on up-rera.in |
| Total Land Area | 25 acres |
| Total Units / Plots | 1,320 apartments across 22 towers of 10 floors each (one aggregator, NoBroker, lists “1 tower,” which is inconsistent with every other source and treated here as a data error) |
| Configuration | 2 BHK and 3 BHK; a “4 BHK available” claim on NoBroker is not corroborated by any other source and is treated as unverified |
| Possession | Listed “Ready to Move” on all major portals since roughly 2011, but Phase III is separately described by one source as still under construction, meaning that status may not apply to the entire complex. Separately and more seriously, physical possession is not the same as legal registration here (see Risk Assessment) |
| Launch Price | Not disclosed: project launched in 2008, predating RERA-mandated BSP disclosure norms, and no archived brochure with original pricing was located |
| Payment Plan | Not applicable: this is now a resale-only market; no construction-linked payment plan was found |
| Current Status | Ready to Move (for most, not necessarily all, of the complex), resale market only, with active, unresolved legal and financial disputes affecting an estimated 500 units, detailed below |
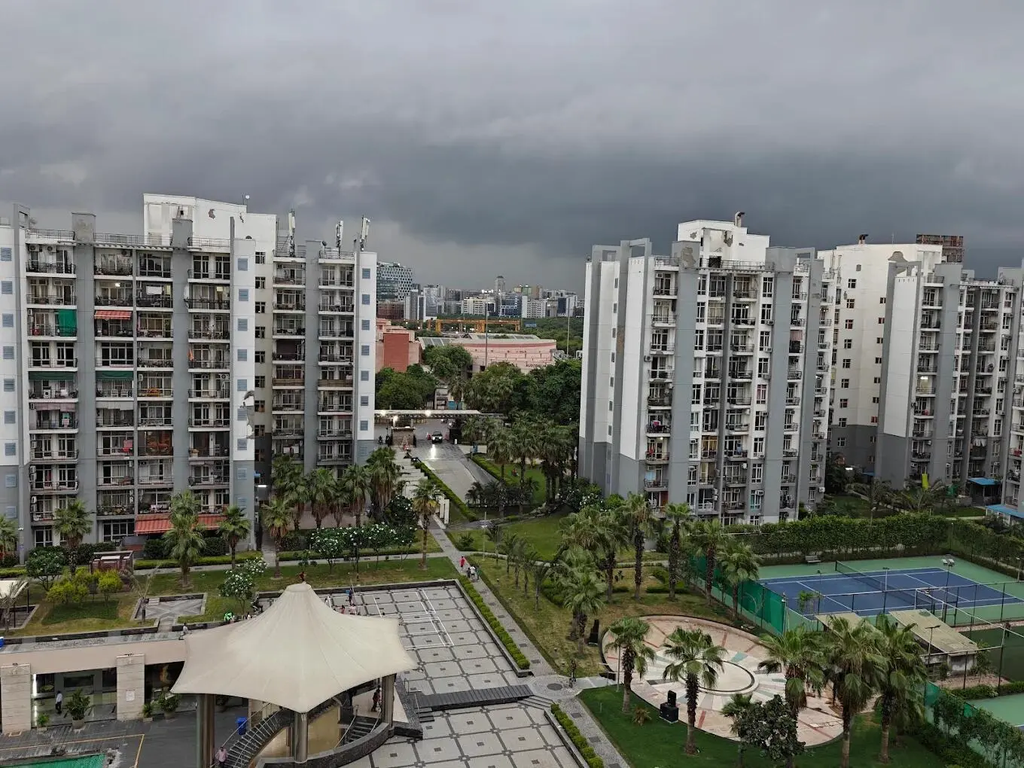
Grand Omaxe is a legacy project: launched in 2008 on the Noida–Greater Noida Expressway in Sector 93B, with residents moving in from 2011 onward. It is large by any measure (1,320 apartments across 22 towers on 25 acres) and today it functions almost entirely as a resale market rather than a live sales operation. There is no builder payment plan to evaluate and no primary launch pricing to benchmark. What a buyer is evaluating instead is a decade-plus-old, occupied society and whatever legal and financial baggage has accumulated around it since.
That baggage is substantial, and it needs to be stated up front rather than buried at the end of this review. In September 2024, Noida Authority sealed unsold flats and roughly 9,000 square metres of vacant land within the project over unpaid dues of ₹457.8 crore owed by the developer, Omaxe Buildhome Limited. As a direct consequence, an estimated 500 existing flat owners have reportedly been unable to register (execute lease deeds for) apartments they already live in. A separate, ongoing Allahabad High Court case is forcing phased deposits to release additional flats for registration, and an older, still-unresolved 2017 dispute over ₹12 crore in maintenance funds sits in the background. None of this means the flats themselves are structurally unsound or that residents are being evicted. But it does mean the most basic thing a property buyer needs, a clean and registerable title, is not guaranteed here without direct verification of the specific unit in question.
Beyond the legal picture, this review also flags a data-quality problem: pricing, unit sizes, and even the RERA registration number for this project vary widely and inconsistently across every aggregator checked. None of these figures should be taken at face value, and this review will not manufacture false precision where the underlying sources disagree.
Key Highlights
- 1,320 apartments across 22 towers of 10 floors each, on 25 acres, consistent across Omaxe’s own site, 99acres, and SquareYards.
- Configurations limited to 2 BHK and 3 BHK; a “4 BHK” listing on NoBroker is not corroborated anywhere else and appears to be a data error.
- Unit sizes are cited inconsistently across sources: 1,110–1,940 sq. ft. per Omaxe.com and 99acres, 1,010–1,940 sq. ft. and separately 2 BHK/3 BHK figures of 1,110/1,940 sq. ft. per SquareYards, and 1,100/1,625 sq. ft. per NoBroker, a spread of 200–300 sq. ft. for what are described as the same configurations.
- Launched in 2008; residents began moving in from 2011; the project now trades almost entirely on the resale/secondary market.
- Listed “Ready to Move” on all major portals, but SquareYards separately describes Phase III as still under construction, meaning “Ready to Move” likely applies to most, not all, of the complex.
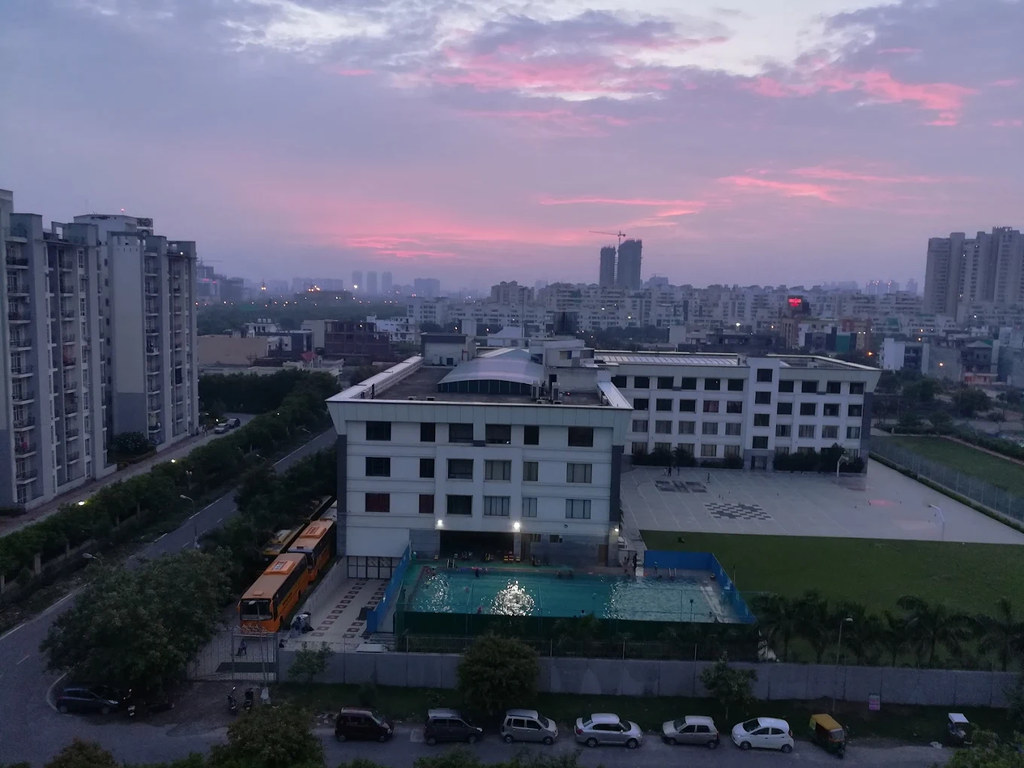
- Fronts the Noida–Greater Noida Expressway directly.
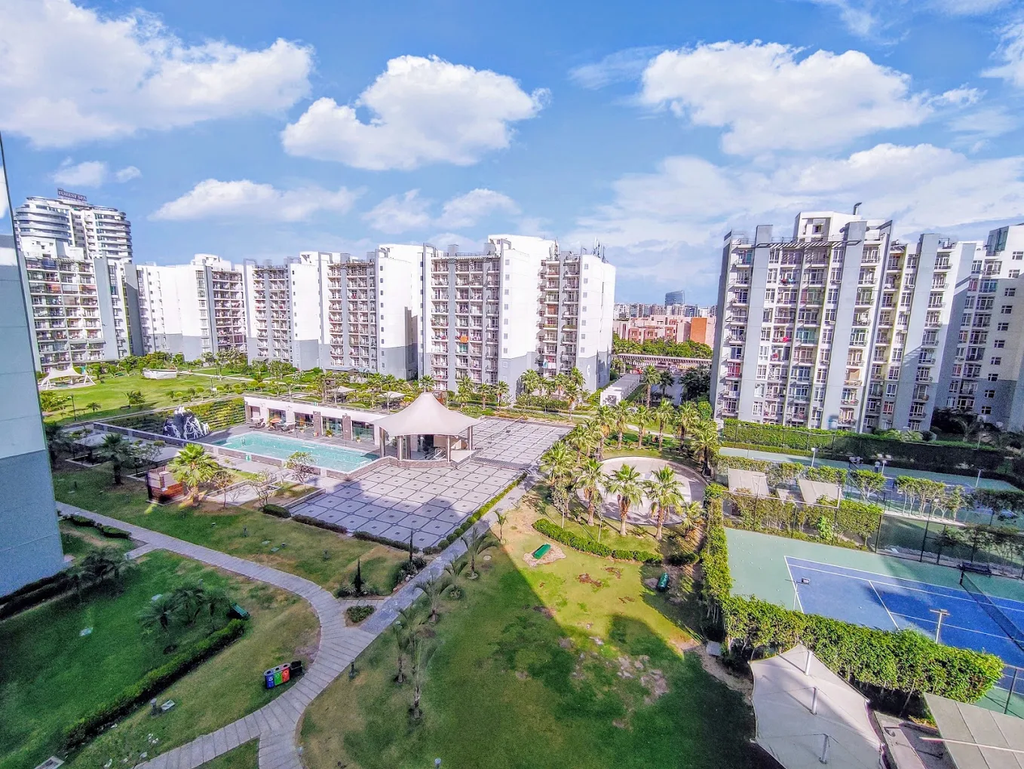
- Marketed as adjoining a “325-acre reserve forest,” a developer/aggregator claim not independently verified against a forest-department source.
- No RERA project registration number could be independently confirmed on up-rera.in. Two conflicting numbers circulate on aggregators, and one (UPRERAAGT10119) carries a prefix format reserved for agent registrations, not projects.
- Noida Authority sealed unsold flats and about 9,000 sq. metres of vacant land within the project in September 2024 over unpaid dues of ₹457.8 crore.
- Approximately 500 flat owners have reportedly been unable to register/execute lease deeds for their apartments as a direct result of that dues dispute, per ConstructionWorld’s September 2024 report.
- Ongoing Allahabad High Court litigation (Tarun Kapoor and 29 Others v. NOIDA, Writ Petition No. 10854 of 2018) requires the developer to make phased deposits (a further ₹25 crore ordered in a 2025 hearing, on top of more than ₹93 crore already deposited) to release additional flats for registration.
- A separate, older dispute: in 2017, Noida Authority directed the developer to hand society maintenance to the Apartment Owners’ Association after residents alleged ₹12 crore in IFMS funds had not been transferred; current resolution status could not be confirmed.
- The operating entity named in Noida Authority notices and the court case is Omaxe Buildhome Limited, a subsidiary, not the listed parent company, Omaxe Limited, that most marketing and brand recognition trades on.
- Omaxe Group operates numerous separate legal entities across cities and projects, a fragmentation pattern that can complicate buyer recourse if something goes wrong.
- The “Grand Omaxe” brand name is reused for unrelated projects in other cities (for example, Lucknow), not connected to this Sector 93B project.
- Current resale asking prices vary enormously across sources: roughly ₹88.80 lakh–₹1.55 crore (SquareYards), ₹1.32 crore–₹2.30 crore (99acres), and ₹1.65 crore–₹2.44 crore (NoBroker).
- Per-sq-ft asking rates are similarly inconsistent even within a single source: SquareYards shows figures ranging from about ₹8,000/sq. ft. to ₹11,900/sq. ft. to ₹14,550–₹14,700/sq. ft. across different data pulls.
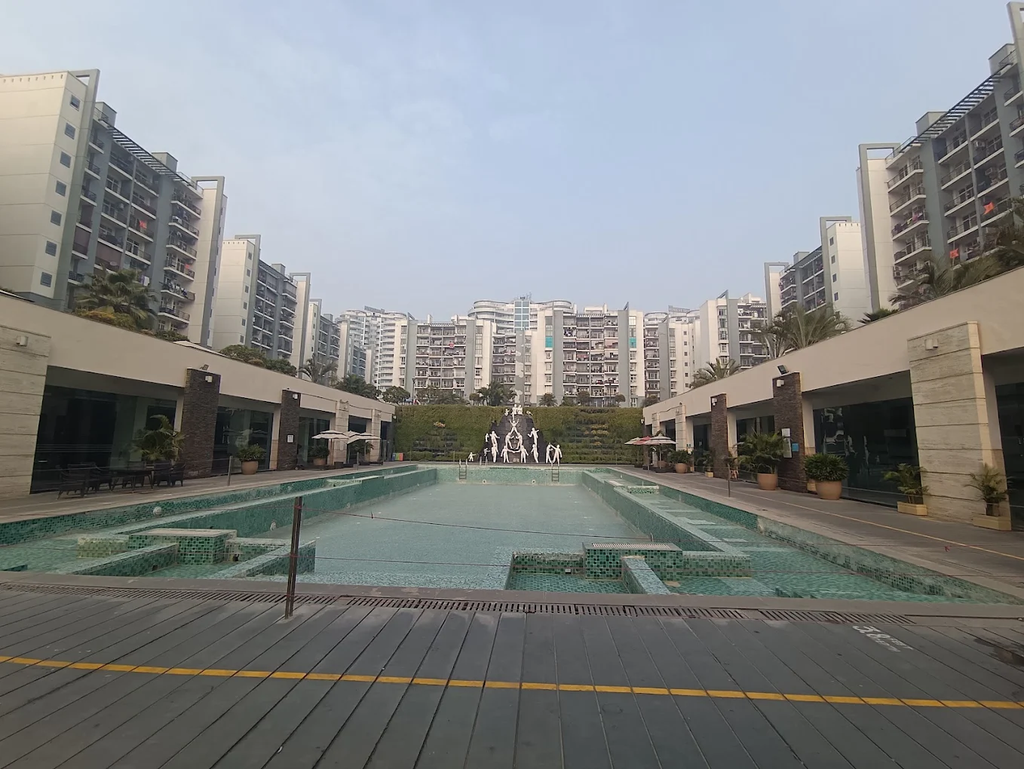
- Amenities listed include a clubhouse, swimming pool, gymnasium, sauna, Jacuzzi, steam room, multi-cuisine restaurant, and a multipurpose sports court. No clubhouse square footage is disclosed anywhere.
- Resident reviews (small samples on both platforms) cite recurring seepage/water intrusion in basements during monsoon as an ongoing maintenance issue.
- Nearest Aqua Line metro stations are cited at roughly 1–1.7 km by locality-level data, but resident reviews put actual travel time at roughly 20 minutes, suggesting straight-line distance understates real access.
- A 2021 law-and-order incident (demolition of illegal encroachment structures linked to an absconding politician) is publicly associated with the project’s name in news coverage; it is not a builder-caused defect but does surface in searches for the project.
- Banking partners cited by the developer include DHFL, a lender that has been under financial distress and restructuring for several years; its current active status as a partner here is unverified.
- Resident review scores diverge sharply by platform: 4.9/5 from 7 reviews on SquareYards versus 3.8/5 from 6 reviews on 99acres; both sample sizes too small to be statistically meaningful.
Amenities
Club & Lifestyle Amenities
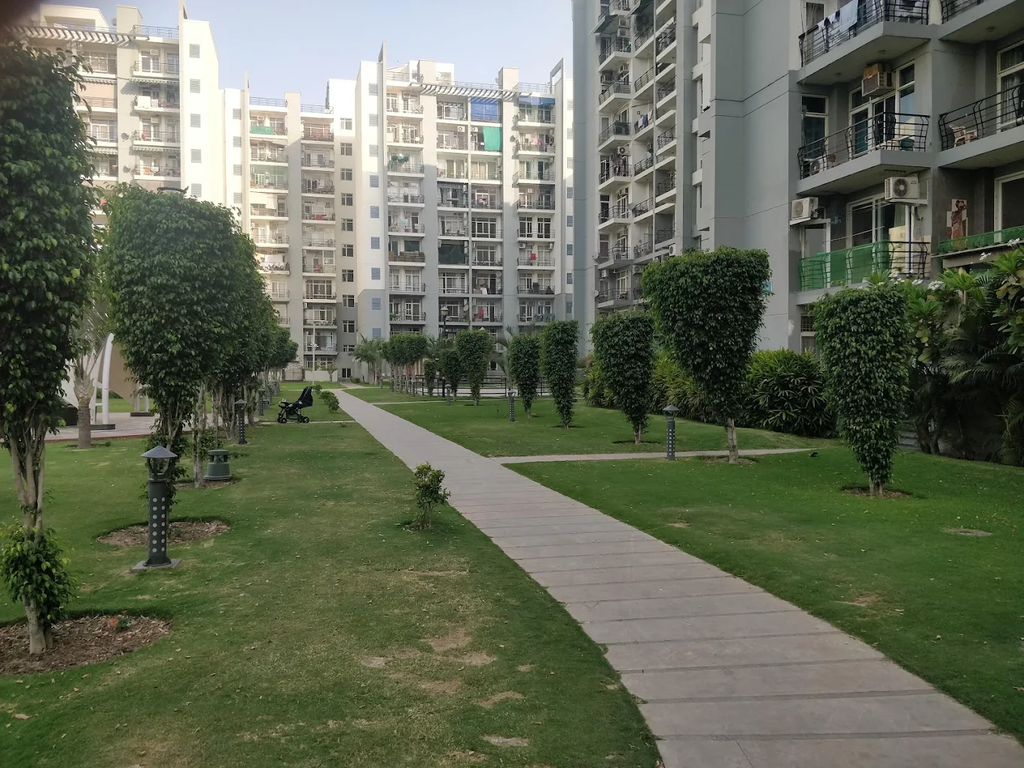
An in-house clubhouse is listed, with no square footage disclosed anywhere reviewed. Per Omaxe’s own site (via a SquareYards fetch), the clubhouse-adjacent facilities include a swimming pool, gymnasium, sauna, Jacuzzi, and steam room, alongside a multi-cuisine restaurant, café/coffee bar, and cafeteria. No source breaks out which of these sit inside a single clubhouse building versus as separate structures across the 25-acre complex.
Sports & Fitness Facilities
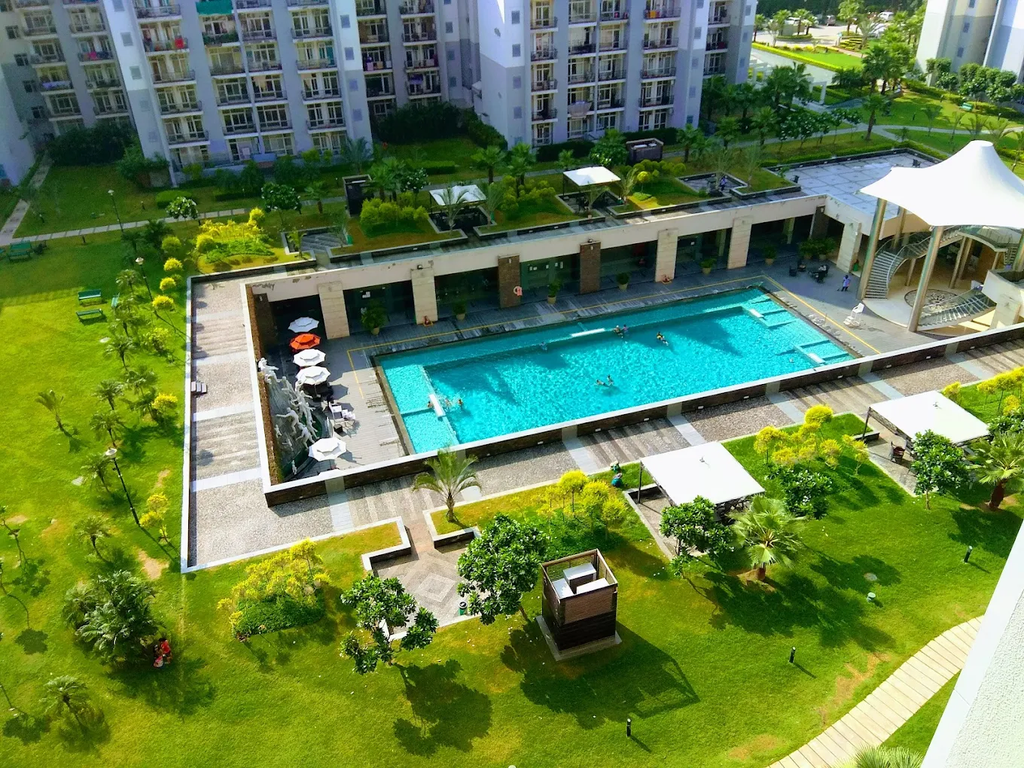
A multipurpose sports court, snooker/pool table, and squash facility are listed. No dimensions, court counts, or current condition were found in any source.
Family & Community Features
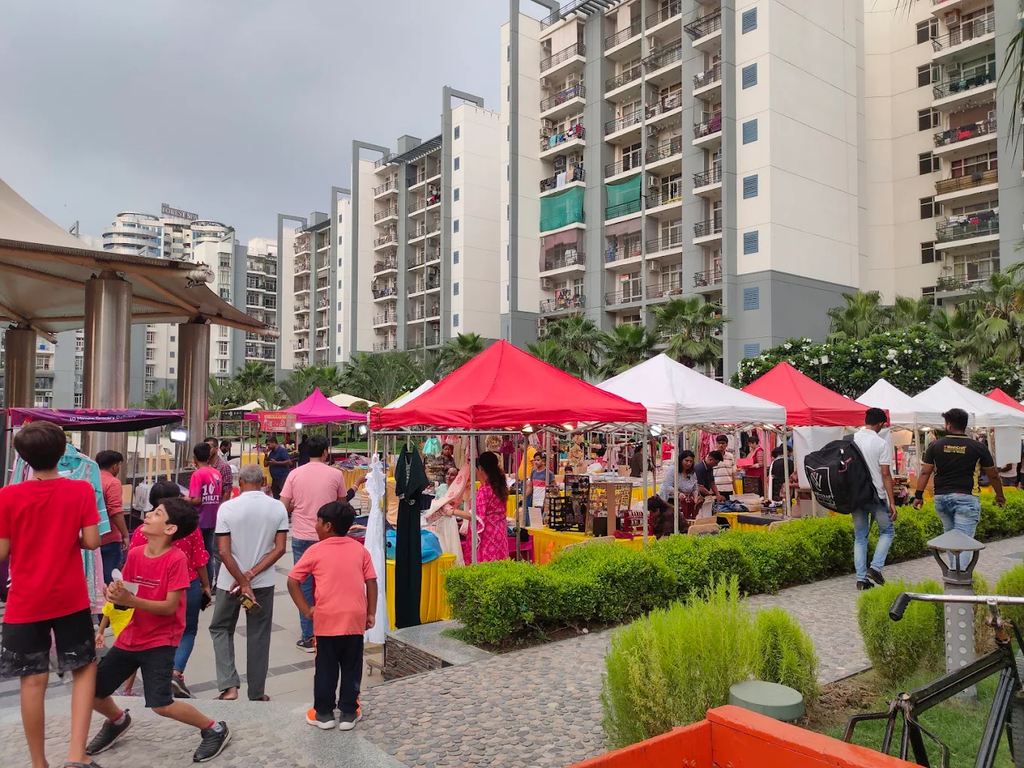
A party lounge and landscaped greenery are cited across listings. One search-synthesis source claims “55–65% dedicated to green areas and parks,” but the attribution is unclear: it reads as developer marketing copy relayed through an aggregator rather than an independently confirmed figure. No dedicated children’s play area, senior-citizen zone, or barbecue area is separately itemized in any source reviewed.
Safety & Convenience
24×7 security, CCTV/video surveillance, power backup, rainwater harvesting, and a sewage treatment plant are listed. The project is also marketed as earthquake-resistant by design and as “Vastu compliant,” both developer/marketing claims; Vastu compliance in particular is not a regulatory certification of any kind and cannot be independently verified. No lift-to-unit ratio or EV charging provision was found in any source.
Retail & Utility
A conference room and an RO water system are listed. No dedicated retail or in-project shopping component was found in any source checked.
What Is Missing: The amenity list here is fairly extensive on paper: clubhouse, pool, sauna, Jacuzzi, multiple sports facilities. But almost none of it comes with a specific number attached. Clubhouse square footage is unspecified. Court counts and dimensions are unspecified. The “55–65% green area” figure has no clear original source. Given that this is a Ready-to-Move, occupied project rather than a pre-launch pitch, a prospective buyer has an advantage a new-launch buyer doesn’t: these amenities can and should be inspected in person before purchase rather than taken on faith from a portal listing.
Prime Location — Grand Omaxe
Grand Omaxe sits in Sector 93B, fronting the Noida–Greater Noida Expressway directly, the project’s clearest, most verifiable location asset. SquareYards’ locality overview for Sector 93B shows genuine demand pressure in the area: demand for apartments is cited as running well ahead of supply (88% demand versus 50% supply), with 2 BHK units the most sought configuration and the ₹50 lakh–₹2 crore band the most active price range. The “adjoining 325-acre reserve forest” framing used in marketing is a real belt of green space referenced by multiple aggregators, but it has not been independently verified against a government forest-department source and should be treated as marketing framing rather than a confirmed fact.
Connectivity is where the marketing and the on-ground reality appear to diverge somewhat. Locality-level data puts the nearest Aqua Line metro stations, Sector 83 and Sector 76, at roughly 1–1.7 km and roughly 1 km respectively; these are figures for the Sector 93 locality generally, not confirmed as measured from the Grand Omaxe gate specifically. Resident reviews on 99acres and SquareYards instead describe actual travel time to a usable metro station as roughly 20 minutes, which points to real driving distance and traffic rather than straight-line proximity. Noida International Airport (Jewar) is under construction region-wide, with general reference points putting it roughly 48–55 km from central Noida (Sector 18); no source was found giving a distance measured specifically from Sector 93B, so any such figure should be treated as a rough regional estimate pending a direct map-tool check.
| Destination | Distance / Drive Time |
|---|---|
| DND Flyway | 19.3 km (aggregator-reported, not map-tool verified) |
| Amity University | 7.3 km (aggregator-reported, not map-tool verified) |
| Max Super Speciality Hospital | 3.3 km (aggregator-reported, not map-tool verified) |
| Genesis Global School | 1.2 km (aggregator-reported, not map-tool verified) |
| Sector 83 Metro Station (Aqua Line) | Approx. 1–1.7 km, locality-level figure, not project-gate-specific |
| Sector 76 Metro Station (Aqua Line) | Approx. 1 km, locality-level figure, not project-gate-specific |
| Nearest metro, resident-reported real travel time | Approx. 20 minutes by road |
| Noida International Airport (Jewar) | Not verified for this specific project; regional estimate only, roughly 48–55 km from Sector 18, Noida |
| Noida City Centre (Sector 39) | Not disclosed in any source checked |
Major Location Advantages
- Direct frontage on the operational Noida–Greater Noida Expressway.
- Demand for apartments in Sector 93B significantly outpaces supply per SquareYards’ locality data.
- Max Super Speciality Hospital within a reported 3.3 km.
- Genesis Global School within a reported 1.2 km.
- Two Aqua Line metro stations (Sector 83 and Sector 76) within a reported 1–1.7 km at the locality level.
What the Marketing Doesn’t Tell You
The 1–1.7 km metro-distance figures commonly quoted for Sector 93B are locality-level numbers, not measurements from the Grand Omaxe gate itself, and resident reviews describing a roughly 20-minute real travel time suggest the practical experience is closer to a drive than a walk. Locality price-trend data is also contradictory: one SquareYards pull shows a 19.39% year-on-year price increase for Sector 93B, while a separate search-synthesis dataset shows a roughly 3.7% year-on-year decline for the same sector; these two figures cannot both be describing the same trend, and neither should be treated as authoritative without a fresh, dated check against live listings. Finally, “Ready to Move” as a project-wide label appears to overstate completion: Phase III is separately described as still under construction, so a buyer should confirm which phase a specific tower belongs to rather than assume the entire 22-tower complex is finished.
Pricing & Configuration
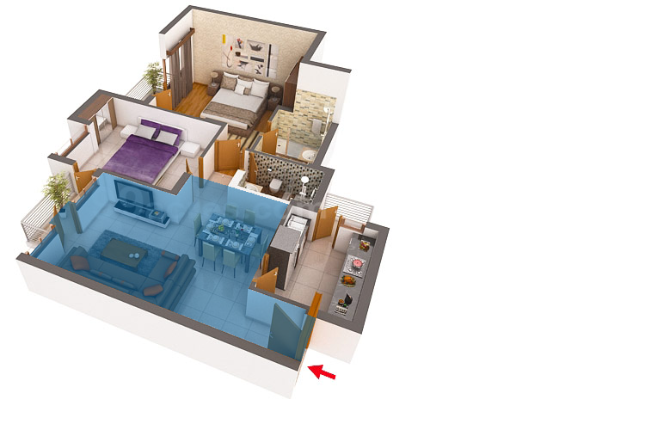
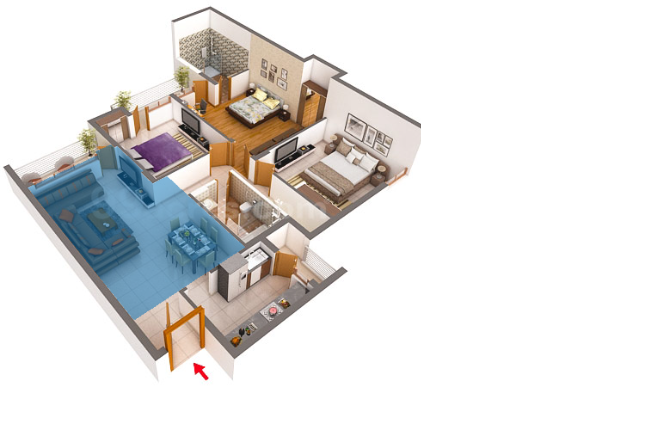
| Configuration | Size (Sq. Ft.) | Starting Price | All-In Estimated Cost |
|---|---|---|---|
| 2 BHK | 1,010–1,110 (cited range; sources vary by 200–300 sq. ft. for the same label) | Not broken out by configuration in any source: see overall project asking range below | Not disclosed: resale transactions are negotiated individually |
| 3 BHK | 1,625–1,940 (cited range; sources vary by 200–300 sq. ft. for the same label) | Not broken out by configuration in any source: see overall project asking range below | Not disclosed: resale transactions are negotiated individually |
No source reviewed splits current asking prices by configuration; the overall project-level asking ranges reported are, themselves, wide and inconsistent: SquareYards cites ₹88.80 lakh–₹1.55 crore (at a stated average of ₹8,000/sq. ft. in one pull, ₹11,900/sq. ft. down 9.8% quarter-on-quarter in another, and a Q4 2025 movement from ₹14,550 to ₹14,700/sq. ft. in a third); 99acres cites ₹1.32 crore–₹2.30 crore; NoBroker cites ₹1.65 crore–₹2.44 crore. A spread from ₹88.80 lakh to ₹2.44 crore across sources, allegedly for comparable unit types, reflects some genuine variance by floor, tower, and facing, but also points to stale or inconsistently maintained aggregator data. This review will not collapse that spread into a single headline number: any buyer should ask for the specific comparable transaction behind whatever figure a broker quotes, not a portal average.
Against that spread, SquareYards’ Sector 93B locality overview cites an average sale price of ₹17,850/sq. ft. for apartments generally, with a claimed 19.39% year-on-year increase, a figure that, as noted above, directly conflicts with a separate dataset showing a roughly 3.7% year-on-year decline for the same sector. Given this contradiction, no confident premium-or-discount calculation can be made here with the data available; a buyer should benchmark against a fresh, dated set of comparable listings rather than either locality figure cited in this research.
Price Includes
Not disclosed by any source checked. This is a resale-only market: there is no developer BSP, and what a quoted price includes (parking, club membership, maintenance deposit) is negotiated between individual buyer, seller, and broker rather than published project-wide.
Additional Charges
- PLC and parking charges: Not disclosed in any source checked.
- IFMS/Maintenance deposit: Not a routine disclosure gap here: a 2017 Noida Authority notice recorded that ₹12 crore in IFMS funds collected from residents had not been transferred to the Apartment Owners’ Association by the developer. Current resolution status as of 2026 could not be confirmed in any source reviewed.
- GST: Not disclosed. Resale transactions of Ready-to-Move properties are generally treated differently from GST-liable under-construction sales under current Indian tax rules, but this was not independently confirmed for this specific project and should be checked with a tax advisor for any individual transaction.
- Registry and stamp duty: Not disclosed. Standard Uttar Pradesh stamp duty and registration rates apply to any Noida resale purchase, but the current statutory rates were not looked up as part of this research and should be confirmed with a lawyer or the sub-registrar’s office. Given that an estimated 500 units at this project reportedly cannot currently execute a lease deed at all, the more urgent question for a buyer here is whether a specific unit can be registered at any rate, not what rate applies.
Payment Plan
Not applicable. Grand Omaxe has no active developer sale and no construction-linked payment schedule for its completed towers. Every current transaction is a resale between private parties, typically settled through a bank loan or a direct payment agreed between buyer and seller.
Builder Profile
| Particulars | Details |
|---|---|
| Legal Entity Name | Omaxe Buildhome Limited, the operating entity named in Noida Authority’s dues-default notice, the September 2024 sealing action, and the Allahabad High Court litigation for this project |
| CIN / Registration Number | U70109DL2006PLC151613 |
| Incorporation Date | Registered circa 2006 |
| Registered Office | 10, Local Shopping Centre, Kalkaji, New Delhi |
| Founder / MD | Not disclosed for the subsidiary directly. Parent company Omaxe Limited’s directors per ZaubaCorp: Rohtas Goel, Nishal Jain, Binitha Manohar Dalal, Shridhar Rao, Aroon Kumar Aggarwal, Vinit Goyal, Mohit Goel; may not reflect the current board |
| Claimed Experience | 32 years, per SquareYards’ relay of the developer’s own claim (parent Omaxe Limited was incorporated 8 March 1989) |
| Delivered Projects | 91 total projects, 72 delivered, per SquareYards’ relay of Omaxe’s own claim; not independently verified against a project-by-project RERA audit. Company-reported delivered-area figures also vary across reporting periods: approximately 132 million sq. ft. as of FY2022-23, approximately 124.3 million sq. ft. as of September 2020, and an earlier figure of 10.68 million sq. ft. across 17 projects |
| Clients Served | Not disclosed |
| Other Entities | Parent: Omaxe Limited (CIN L74899HR1989PLC051918, incorporated 8 March 1989, listed on BSE and NSE). Group also includes, among others found during research: Omaxe Indore Developers Limited, Omaxe India Trade Centre Private Limited, Omaxe Heritage Private Limited, Omaxe World Street Private Limited, Omaxe Housing And Developers Limited, Omaxe Chandigarh Extension Developers Pvt. Ltd., Omaxe New Chandigarh Developers Pvt. Ltd. |
Grand Omaxe was built and is legally accountable through Omaxe Buildhome Limited, a wholly owned subsidiary of the listed parent, Omaxe Limited. This distinction matters directly to this review: the “Omaxe” brand recognition, the 32-years-of-experience claim, and the 91-projects claim all trade on the parent’s public profile, but the entity actually named in every document tied to this project’s troubles (the Noida Authority dues notice, the sealing order, and the Allahabad High Court case) is the subsidiary. A buyer’s contractual and legal recourse runs to Omaxe Buildhome Limited, not automatically to the listed parent, which is a meaningfully different risk profile than “buying from a BSE-listed company” implies.
The wider Omaxe group’s track record outside this specific project also shows a documented pattern of regulatory friction, not an isolated incident. Punjab RERA ordered Omaxe New Chandigarh Developers Pvt. Ltd. to pay ₹34.81 lakh in delayed-possession interest for its “The Lake” project, where buyers had booked more than a decade earlier and still hadn’t received possession, and separately directed the same entity to pay delay-interest on its “Caspean E” project at the same township. Punjab RERA also directed a sister entity, Omaxe Chandigarh Extension Developers Pvt. Ltd., to pay ₹7.87 lakh to a homebuyer for a separate possession delay. None of these orders concern Grand Omaxe directly, but they establish that possession delays and dues disputes recur across multiple Omaxe group entities in different cities, which is relevant context when weighing how the group has handled its obligations at this specific project.
At Grand Omaxe itself, the record is more serious than delayed possession. The September 2024 sealing action over ₹457.8 crore in unpaid dues, the resulting inability of roughly 500 owners to register their flats, the ongoing Allahabad High Court case requiring phased deposits to release units for registration, and the unresolved 2017 dispute over ₹12 crore in IFMS funds together describe a developer that has, at minimum, struggled for years to meet its financial obligations to the land authority and to residents on this specific project. Resident satisfaction scores, for what they’re worth given the tiny sample sizes (4.9/5 from 7 reviews on SquareYards, 3.8/5 from 6 reviews on 99acres), and a recurring complaint about basement seepage during monsoon, round out a picture of a physically functioning but administratively troubled society.
Risk Assessment — Positive Factors
- 1,320 units already built and occupied, with the society functioning as an established residential community since roughly 2011, not a construction-stage bet.
- Direct frontage on the operational Noida–Greater Noida Expressway.
- Demand for apartments in Sector 93B significantly outpaces supply per SquareYards’ locality data (88% demand versus 50% supply), a locality-level signal of ongoing buyer interest in the area.
- Active resale transaction volume: SquareYards cites 74 registered resale transactions worth ₹62 crore through August 2026 (a separate pull on the same portal cites 52), indicating a functioning, liquid resale market rather than a dormant listing.
- Resident reviews on SquareYards (small sample, 7 reviews) rate the project 4.9/5, with positive comments on RWA and society management, connectivity, construction quality, and greenery.
- Parent company Omaxe Limited is a listed entity on both BSE and NSE with an operating history since 1989, which brings a degree of financial disclosure and public visibility that many private, unlisted developers do not carry, though this scrutiny applies to the parent, not automatically to the subsidiary that built and is legally accountable for this project.
Risk Assessment — Limitations
- No RERA project registration number could be independently confirmed on up-rera.in. Two conflicting numbers circulate on aggregators, and one (UPRERAAGT10119) carries a prefix format used for agent registrations, not project registrations.
- Noida Authority sealed unsold flats and roughly 9,000 sq. metres of vacant land within the project in September 2024 over ₹457.8 crore in unpaid dues owed by the developer, and as a direct consequence, an estimated 500 existing flat owners have reportedly been unable to register/execute lease deeds for units they already occupy.
- Ongoing Allahabad High Court litigation (Tarun Kapoor v. NOIDA) requires the developer to make further phased deposits (₹25 crore ordered in a 2025 hearing, on top of more than ₹93 crore already deposited) before additional flats are released for registration; this is an active, unresolved legal process as of the most recent report found.
- A 2017 dispute over ₹12 crore in IFMS funds allegedly not transferred to the Apartment Owners’ Association remains unresolved in every source checked; current status could not be confirmed.
- No license/lease approval number for the underlying land was found published anywhere: directly relevant given that the dues dispute concerns the land-lease terms themselves, and a buyer’s lawyer needs to pull this directly from Noida Authority records.
- Asking prices vary enormously across aggregators (from roughly ₹88.80 lakh to ₹2.44 crore for comparable unit types), a spread wide enough to reflect stale or unreliable data as much as genuine floor/facing variance.
- Locality-level price-trend data directly contradicts itself (a claimed 19.39% year-on-year increase in one source versus a roughly 3.7% year-on-year decline in another for the same sector), meaning no confident premium-or-discount claim can currently be made with the available data.
- Unit sizes for the same configuration label vary by 200–300 sq. ft. across sources, meaning the per-sq-ft price a buyer calculates depends heavily on which portal’s size figure is used.
- The entity operationally accountable for this project’s disputes is Omaxe Buildhome Limited, a subsidiary, not the listed parent, Omaxe Limited, that most brand recognition and marketing trades on.
- The wider Omaxe group has a documented history of RERA enforcement action for possession delays at other projects (Punjab RERA penalties against Omaxe New Chandigarh Developers and Omaxe Chandigarh Extension Developers), indicating the dues/delay pattern at Grand Omaxe is not an isolated incident within the group.
- Marketed metro proximity (1–1.7 km, locality-level) conflicts with resident-reported real travel time of roughly 20 minutes to the nearest usable station.
- With title/registration currently blocked for an estimated 500 units, any buyer purchasing into that pool could inherit the same inability to register, a direct threat to resale liquidity, not merely an inconvenience.
- “Ready to Move” status does not appear to cover the entire complex: Phase III is separately described as still under construction, so completion should be confirmed at the specific tower level, not assumed project-wide.
- Distance and connectivity figures cited in this research are aggregator-reported, not map-tool verified from the actual project address, and should be re-confirmed before being relied on for a purchase decision.
The Hidden Information Between the Lines
The RERA registration confusion here is worth unpacking rather than dismissing as routine aggregator sloppiness. UP-RERA’s project registration numbers generally use a “PRJ” designation, while “AGT” designates an agent or channel-partner registration, meaning the UPRERAAGT10119 number circulating on SquareYards for this project is very likely a broker’s registration number that has been mislabeled as the project’s own. Separately, Grand Omaxe was launched in 2008, predating UP RERA’s 2016–17 entry into force, and one source describes Phase III as the only portion still under construction. Under RERA, only the incomplete, ongoing portion of a project generally requires registration, so it is plausible that most of this project genuinely falls outside RERA’s mandate, which would be a legally unremarkable situation rather than a red flag on its own. But that is a different and more nuanced fact than what a portal displaying a plausible-looking RERA number suggests to a buyer glancing at a listing, and it does not change the fact that no number found for this project could actually be confirmed.
The more consequential story is the land underneath the buildings, not the buildings themselves. Noida Authority allots land to developers on a leasehold basis, with dues payable over time; a developer that sells and delivers flats to buyers while falling behind on those lease payments to the authority creates a gap between what a buyer has paid for and what the authority will formally register. That is precisely what appears to have happened here: Omaxe Buildhome Limited owed ₹457.8 crore, failed to pay even the reduced 25% required after a COVID-era relief package, and the Authority responded by sealing unsold inventory and vacant land. Roughly 500 buyers who had nothing to do with that default are the ones currently unable to register titles to homes they already live in. The Allahabad High Court case exists specifically because this dispute has dragged on for years, with the court ordering deposits in tranches (₹93-plus crore already paid, a further ₹25 crore ordered in 2025) to release flats for registration piece by piece rather than all at once.
The entity structure adds a layer that a buyer glancing at “Omaxe” marketing material would not necessarily catch. Omaxe Limited is the listed, publicly recognized brand; Omaxe Buildhome Limited, a separate legal person and wholly owned subsidiary, is the entity actually named in every dispute connected to this project. This is not an unusual corporate structure for a large developer group, but it does mean that the financial and legal accountability for Grand Omaxe’s problems sits with a subsidiary whose own financial disclosures are far less visible to the public than the parent’s BSE/NSE filings, a gap between brand-level reassurance and entity-level accountability that is easy to miss without specifically checking which company signed the original allotment and which company is named in the court case.
The pricing and sizing chaos across aggregators is also worth treating as a signal rather than noise. For a project this thoroughly documented in legal and financial trouble, it would be reasonable to expect careful, current listing data; instead, unit sizes vary by 200–300 sq. ft. for the same configuration label, asking prices range from ₹88.80 lakh to ₹2.44 crore across sources, and locality price trends contradict each other within the same portal’s own data pulls at different times. That level of inconsistency suggests listings here are stale or loosely maintained, which matters because a buyer relying on any single portal’s number is working from an unreliable input on one of the largest financial decisions they will make.
Finally, it’s worth connecting two disputes seven years apart rather than treating them as unrelated: the 2017 allegation that ₹12 crore in resident-paid IFMS funds had not been transferred to the Apartment Owners’ Association, and the 2024 sealing action over ₹457.8 crore in unpaid land dues. Different funds, different counterparties, but the same pattern: money that residents or the developer’s own financial obligations to a public authority appear to have been deprioritized relative to other calls on the company’s cash. Neither dispute alone proves systemic mismanagement, but together they describe a developer that has, on this specific project, repeatedly fallen behind on financial obligations tied directly to the residents living there.
Questions to Consider Before Investing
- Can you produce a UP-RERA project registration number for this specific unit or tower that I can verify directly on up-rera.in today, or confirm in writing that this unit falls outside RERA’s registration requirement due to pre-2017 completion?
- Has Noida Authority’s ₹457.8 crore dues claim against Omaxe Buildhome Limited been fully or partially resolved, and can you provide documentation confirming this specific unit is not among the sealed or dues-encumbered inventory?
- Is this specific flat one of the approximately 500 units currently unable to register a lease deed, and if so, what is the realistic timeline and deposit required to release it?
- What is the current status of the Allahabad High Court case (Tarun Kapoor and 29 Others v. NOIDA), and has the court-ordered phased deposit schedule been met on time by the developer?
- Has the 2017 dispute over ₹12 crore in IFMS funds been resolved, and can the Apartment Owners’ Association confirm in writing that those funds were received?
- Which legal entity will actually sign the transfer/sale agreement for this unit (Omaxe Buildhome Limited, the current registered owner, or another party), and what is that entity’s current financial standing?
- Can you show me a current, dated valuation or comparable transaction (not an aggregator average) supporting the specific per-sq-ft price being quoted, given how widely prices vary across portals for this project?
- What is the exact carpet area of this specific unit, verified against the original builder-buyer agreement rather than a portal listing, given sizes vary by 200–300 sq. ft. across sources for the same configuration label?
- Is this unit located in a phase or tower that is fully complete, or does it fall within the Phase III component described as still under construction?
- Will any bank pre-approve a home loan against this specific unit, given the registration and title complications documented for this project, and can that pre-approval be obtained before any payment is made?
- Has the basement seepage issue reported by residents been resolved for this specific tower, and can maintenance records be reviewed before purchase?
- Is the Apartment Owners’ Association current on its own obligations to Noida Authority and any other statutory bodies, and can it share its latest financial statements?
Who Should Consider This Project
- Cash buyers who do not need bank financing and can absorb the risk of a title or registration delay, since this project’s documented disputes could complicate loan approval and add unpredictable timelines.
- End-use buyers targeting a specific unit that has been confirmed, in writing and through independent legal verification, to fall outside the roughly 500-unit blocked list and free of the Noida Authority dues encumbrance.
- Long-horizon buyers prepared to wait out the resolution of the Allahabad High Court litigation and the underlying dues dispute, rather than needing a quick, clean registration on a fixed timeline.
- Buyers who value an established, decade-plus-old, occupied community with existing social infrastructure over a newer project, and who are willing and able to carry out the legal diligence a legacy, disputed project like this demands.
- Investors buying specifically at a discount that reflects these documented risks and disputes, rather than at a price benchmarked against unencumbered comparable resale stock in the same locality.
Who Should Not Consider This Project
- Buyers dependent on a home loan, since the unresolved dues dispute and the blocked-registration status affecting an estimated 500 units create real, unresolved uncertainty around whether a lender will approve financing against a specific unit here.
- Short-term investors seeking a quick, clean resale, given the inconsistent pricing data across aggregators and the added friction any documented legal dispute creates for a fast exit.
- Risk-averse or first-time buyers who want a straightforward transaction and are not prepared to independently verify RERA status, dues clearance, and lease-deed registrability before signing anything.
- Buyers who cannot personally fund an independent legal review before purchase: a title search, a dues-clearance confirmation from Noida Authority, and a check on the current status of the Allahabad High Court case.
- Anyone unwilling to accept that “Ready to Move” and physical possession do not, at this project, guarantee the ability to register the property in their own name on a normal timeline.
Honest Verdict
What genuinely works at Grand Omaxe is the physical reality: 1,320 apartments, occupied since roughly 2011, functioning as a real, lived-in community with amenities, resale transaction activity, and resident reviews that, for whatever the small sample sizes are worth, skew positive on society management and connectivity. This is not a paper project or a stalled construction site. People live here, and the direct expressway frontage and locality-level demand data suggest genuine, ongoing buyer interest in the area.
The core problem is not the buildings. It is the land underneath them and the money owed on it. Omaxe Buildhome Limited’s failure to pay ₹457.8 crore in dues to Noida Authority resulted in an actual sealing action in September 2024, has left roughly 500 existing owners unable to register titles to homes they already occupy, and is still working through the courts years after the original 2018 filing, with fresh deposit orders as recently as 2025. That is not a documentation inconvenience. It is a live, unresolved threat to the one thing a buyer is fundamentally purchasing when they buy property: clear, transferable title.
The practical guidance follows directly from that: do not trust any single aggregator’s price, size, or RERA figure for this project; every one of them conflicts with another source, sometimes within the same portal. Before paying anything, get written, dated confirmation, ideally through a property lawyer, that the specific unit under consideration is not among the sealed or dues-encumbered inventory; check the current status of the Allahabad High Court case directly; and get the Apartment Owners’ Association’s position on the still-unresolved 2017 IFMS dispute. If a bank declines to lend against a specific unit here, treat that refusal as information, not an obstacle to negotiate around.
A decade-old society with working lifts, a swimming pool, and a resale market that still moves units is not the same thing as a decade-old society with clean, registerable title. At Grand Omaxe, right now, only the first of those two has been confirmed.
Disclaimer: This analysis is based on publicly available information gathered through independent research as of September 14, 2026. No financial advice is implied. Always consult a RERA-registered real estate agent and an independent property lawyer before making any real estate investment.