Noida, Uttar Pradesh — Sector 50
Introduction
| Feature | Details |
|---|---|
| Project Name | Purvanchal Silver Estate |
| Developer | Purvanchal Construction Works Private Limited (CIN U74899DL1994PTC061109) — identified by RealEstateIndia.com as the entity behind this project; a second, later-incorporated entity, Purvanchal Projects Private Limited, is also associated with the Purvanchal brand and appears on some listings for this project. See Builder Profile for why this matters. |
| Location | Plot No. F-29, Sector 50, Noida, Uttar Pradesh, on/near Golf Marg (some listings give the micro-address as “Jacaranda Ln, F Block, Sector 50”) |
| Project Type | Residential Apartments |
| RERA Number | Not verified. Aggregators show three different, mutually inconsistent numbers (see Risk Assessment); none could be confirmed on up-rera.in in this research pass. |
| Total Land Area | Conflicting across sources — 4.00 acres vs. 4.87 acres. Not resolved. |
| Total Units / Plots | 106 apartments (consistent across nearly all sources) |
| Configuration | Predominantly 3 BHK and 4 BHK; some sources also list 2 BHK, 5 BHK, and an unverified “6 BHK” resale listing |
| Possession | Claimed as May 15, 2008 or December 1, 2008 (aggregator sources); one developer-track-record profile lists 2005. Not a RERA-committed date — the project predates the RERA Act. |
| Launch Price | Not disclosed anywhere found. No original BSP or builder payment plan is documented for this project. |
| Payment Plan | Not applicable. This is a 100% resale transaction market — there is no active builder-linked, construction-stage payment plan to report. |
| Current Status | Ready to Move — transacting exclusively as resale, not as new inventory sold by a builder |
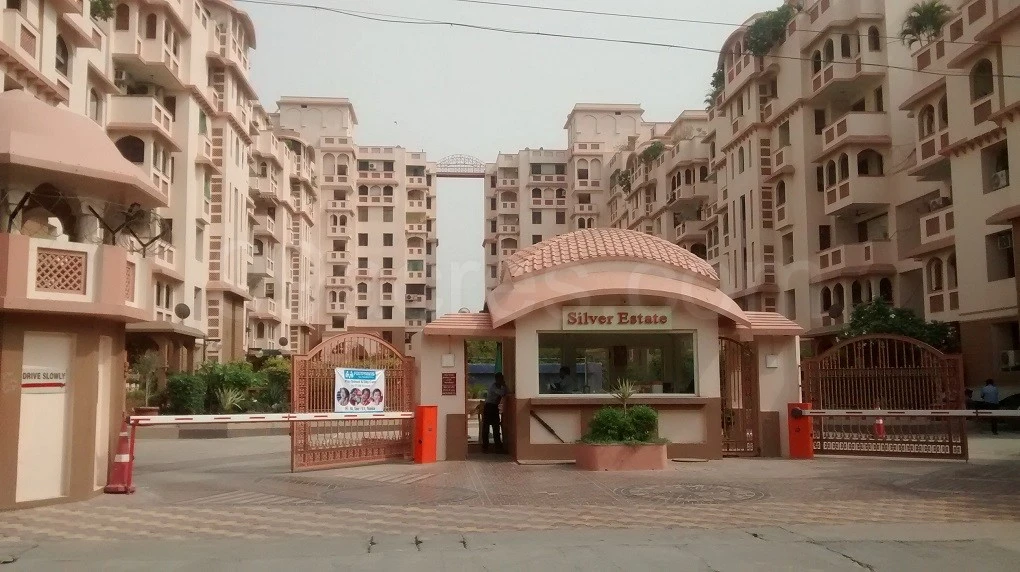
Purvanchal Silver Estate is not a new launch. It is an 18–20-year-old, fully delivered residential society in Sector 50, Noida, and every unit that changes hands today does so as a private resale between an existing owner and a buyer, not as a fresh booking against a builder’s construction-linked plan. That single fact changes how this review has to be read: sections that a newer project review would normally spend on BSP pricing, construction-linked payment stages, and RERA possession commitments mostly do not apply here, because none of those mechanisms exist for a project this old.
That does not mean this review has less to flag. Independent research across property aggregators, the MCA company registry, and public affidavit records turned up three concerns worth stating up front rather than burying at the end. First, no consistent or verifiable RERA registration number could be found for this project across any source checked; the numbers that do appear contradict each other and, in one case, look like an obvious placeholder value. Second, the Purvanchal brand’s project attribution is split across two separate legal entities, one incorporated in 1994 and one in 2010, and the later entity cannot have built a project that was delivered years before it existed. Third, the promoter most closely associated with the current flagship entity, Shah Alam (also known publicly as “Guddu Jamali”), has a pending criminal case disclosed in his own 2022 election affidavit.
None of this means the physical apartments at Silver Estate are defective. The location is genuinely strong, and current resale pricing tracks the broader Sector 50 market reasonably closely. But a buyer evaluating this project deserves to see the accountability and documentation gaps clearly before deciding, and that is what this review sets out to do.
Key Highlights
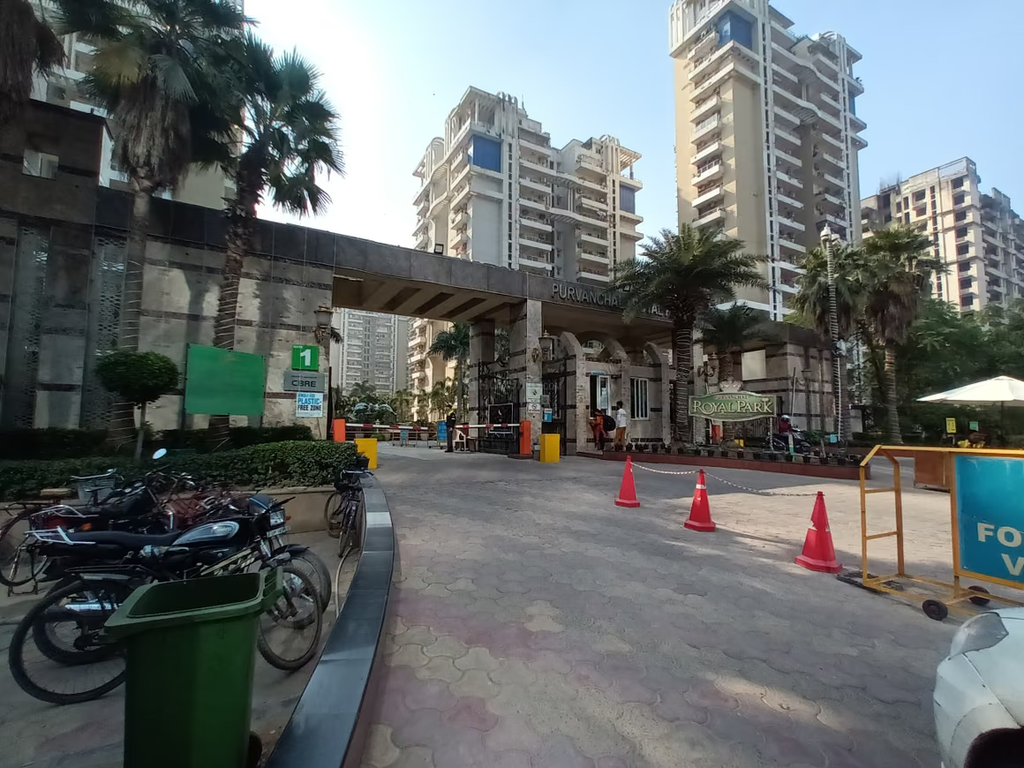
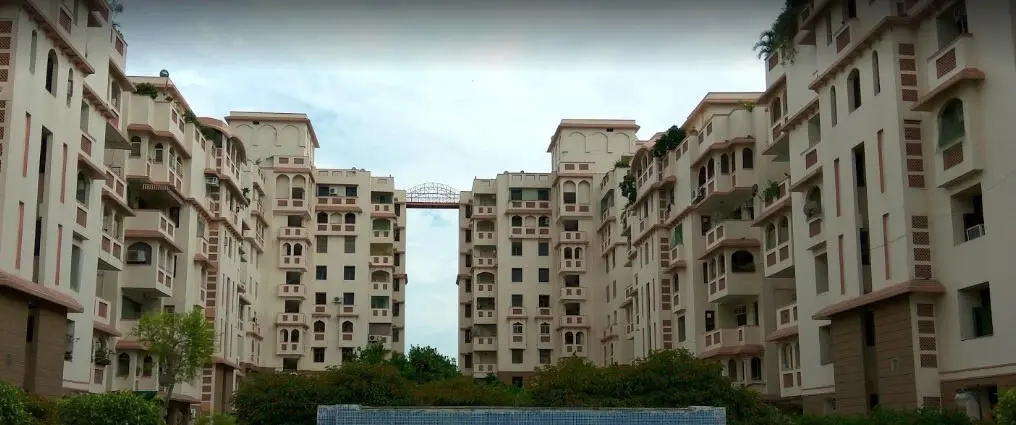
- Sector 50 is a mature, centrally located Noida sector on Golf Marg, not a peripheral or under-construction micro-market.
- The project sits within roughly 0.65 km of Noida Sector 50 (“Rainbow”) metro station on the Aqua Line, per aggregator distance data.
- Golf Course metro station on the Blue Line is also reported to be in the vicinity. That would put two separate metro lines within reach, but this proximity claim has not been map-tool-verified independently.
- IGI Airport is approximately 32–38 km by road depending on terminal and source, roughly a 45–55 minute drive. Figures vary meaningfully across distance calculators, so treat this as a range, not a precise number.
- The project comprises 106 apartments. This figure is consistent across nearly every source checked.
- Configurations are predominantly 3 BHK (approximately 1,550–1,735 sq. ft.) and 4 BHK (approximately 2,700–2,800 sq. ft.).
- One source (NoBroker) lists an implausible “4+ BHK” unit at 8,413 sq. ft., not corroborated elsewhere and likely a data error.
- One resale listing describes a “6 BHK” unit at over ₹12 crore, an unusual configuration, possibly a combined or duplex unit rather than standard stock.
- Land area is reported inconsistently: 4.00 acres by one 99acres summary versus 4.87 acres cited by Square Yards, gharpe.com, and investormart.co.in.
- Tower/block count is wildly inconsistent across sources: one tower (NoBroker, gharpe), seven towers (investormart), and ten towers (Square Yards) have all been cited for the same project.
- Possession is claimed as 2005, May 2008, or December 2008 depending on the source. None of these are backed by a RERA document, since the project predates RERA entirely.
- RERA registration could not be verified. NoBroker shows “UPRERAPRJ1627,” Square Yards shows “UPRERAAGT10119” (the “AGT” prefix is UP-RERA’s convention for agent, not project, registrations), and gharpe.com shows “RAJ-123456789,” a Rajasthan-format placeholder number for a Uttar Pradesh project.
- The project’s claimed possession year (2005/2008) predates both the RERA Act (2016) and UP-RERA’s operational rollout (2017), which is consistent with genuine non-registration rather than concealment. That said, this remains unconfirmed and should be checked directly with UP-RERA before transacting.
- Two distinct legal entities are associated with the Purvanchal brand: Purvanchal Construction Works Private Limited (incorporated 1994) and Purvanchal Projects Private Limited (incorporated 2010). RealEstateIndia.com attributes Silver Estate to the older entity.
- Purvanchal Projects Private Limited’s 2010 incorporation date is later than this project’s own claimed 2005/2008 delivery. The newer entity cannot have built a project completed before it existed.
- Shah Alam, Chairman and Managing Director of Purvanchal Projects Private Limited, is a sitting Uttar Pradesh MLC with a pending criminal case (FIR No. 0234/2020, IPC Sections 354A, 354B, and 506) disclosed in his own 2022 election affidavit.
- News reports describe the underlying allegation as including a claim that Alam was involved in registering expensive flats at below-market rates, a financial-irregularity allegation, not an adjudicated finding.
- Current resale pricing (Q3 2025, per 99acres) moved from approximately ₹15,950/sq. ft. to ₹16,400/sq. ft., a 2.82% quarter-on-quarter increase.
- This pricing sits within, or modestly above, the broader Sector 50 range of ₹11,750–16,700/sq. ft., fairly priced for the locality rather than a premium or discount outlier.
- Only two government-registered resale transactions totaling roughly ₹4 crore were recorded over the prior 12 months per Square Yards, thin transaction volume for a 106-unit society.
- No exact square footage is disclosed for the clubhouse or any named amenity across any source checked.
- No project-specific buyer complaints were found in this research pass, though this reflects the limits of a single search-based research session, not a confirmed clean record.
- Sector 50 flats have appreciated 6.4% over one year, 67.9% over three years, and 102.9% over five years, per 99acres trend data.
Amenities
The amenities below are aggregated from listing claims across 99acres, Square Yards, NoBroker, investormart.co.in, and dm8.in. None have been independently inspected, and no source discloses exact specifications for any facility.
Club & Lifestyle Amenities
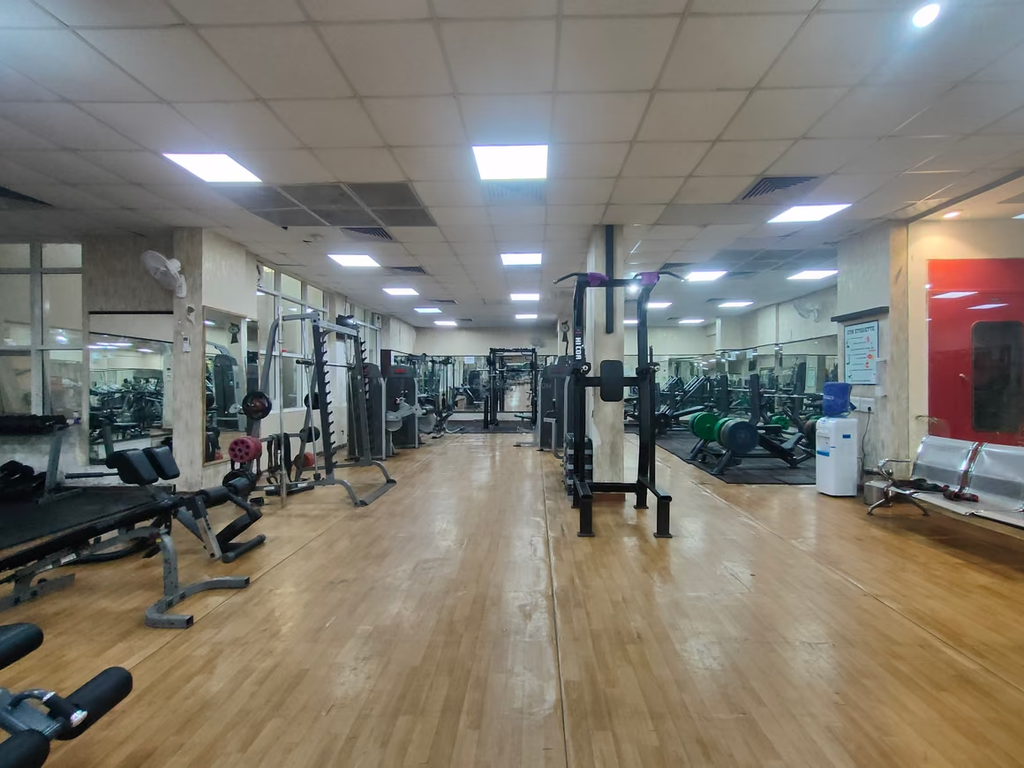
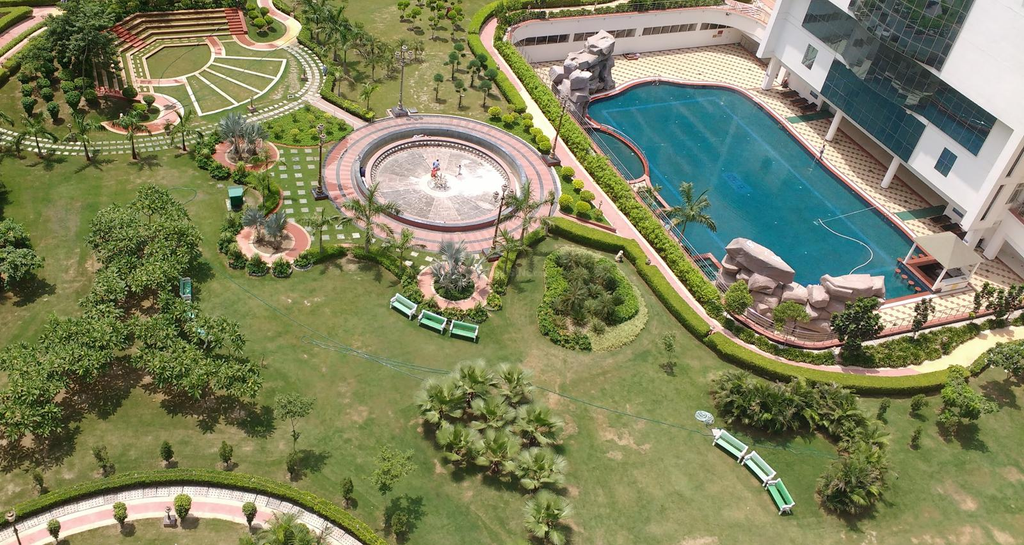
- Swimming pool
- Gymnasium
- Clubhouse / community hall (no square footage disclosed by any source)
Sports & Fitness Facilities
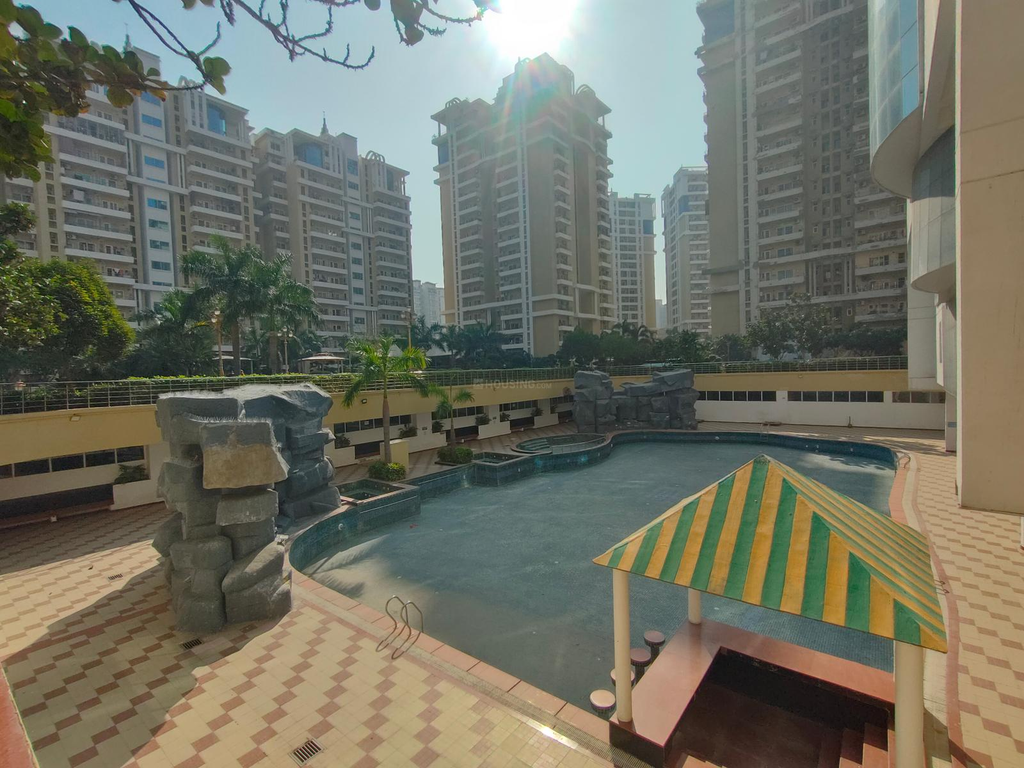
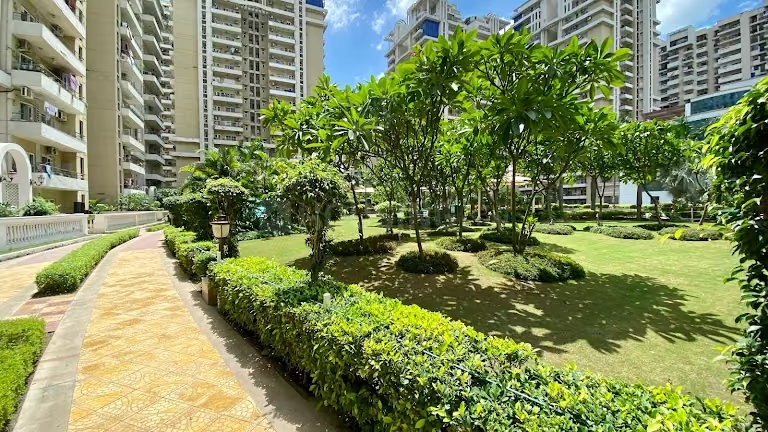
- Badminton court
- Tennis court
- Basketball court
- Volleyball court
- Jogging / strolling track
Family & Community Features
- Children’s play area
- Landscaped garden / park
Safety & Convenience
- 24×7 security with CCTV
- Intercom and video door security
- Fire safety / fire-fighting system
- Power backup
- Lifts
- Covered and visitor car parking
Retail & Utility
- Sewage treatment plant (STP)
- Rainwater harvesting
- Waste disposal system
- 24-hour water supply (corporation supply plus borewell)
- Maintenance staff
- Wi-Fi connectivity (claimed by one source only)
- Solar lighting (claimed by one source only)
- Shopping complex / retail component (claimed by one source only)
What Is Missing: No source (not the aggregators, not the developer’s own materials) discloses the exact square footage of the clubhouse or any individual named facility. “Vastu-compliant layout” appears as a marketing claim with no specification behind it. Several amenities (Wi-Fi, solar lighting, retail) are each claimed by only a single aggregator and are not corroborated elsewhere, which suggests they may be either outdated, aspirational, or simply inconsistent data entry rather than confirmed features of the actual, delivered society. For an 18–20-year-old project, a prospective buyer should verify current amenity condition and functionality directly with the Resident Welfare Association (an active ApnaComplex page for the project suggests one exists) rather than relying on any listing site’s description, since amenities in aging societies commonly degrade or get repurposed over time.
Prime Location — Purvanchal Silver Estate
Sector 50 is one of Noida’s more established, centrally located residential sectors. It sits on Golf Marg, not on the city’s outer expressway corridors. This is a mature micro-market with functioning social infrastructure already in place, which stands in contrast to many newer Noida Extension or Yamuna Expressway projects that carry infrastructure-timeline risk. The sector’s proximity to two separate metro lines is a genuine structural advantage, though the precise walking or driving distances cited by aggregators should be treated as approximate rather than exact, since none were verified against an independent map tool in this research pass.
Beyond connectivity, several “nearby landmark” distances circulated by listing sites for this project could not be trusted at face value. One aggregator (gharpe.com) listed landmarks such as a bank and a hospital as being located “in Delhi” for a project that sits in Noida, a strong indicator of templated or auto-generated content rather than real geodata. Readers should treat any specific landmark distance quoted below as an aggregator claim pending independent map verification, not as a confirmed fact.
| Destination | Distance / Drive Time |
|---|---|
| Noida Sector 50 (“Rainbow”) Metro Station, Aqua Line | ~0.65 km (aggregator-cited, not map-verified) |
| Golf Course Metro Station, Blue Line | In the vicinity (exact distance not independently confirmed) |
| IGI Airport, Delhi | ~32–38 km / ~45–55 min drive (range varies by source and terminal) |
| Noida City Centre | ~1.71 km (aggregator-cited, not map-verified) |
| Manav Rachna School | ~0.17 km (aggregator-cited, not map-verified) |
| Ashwini Hospital | ~0.63 km (aggregator-cited, not map-verified) |
| Amity University | ~4.66 km (aggregator-cited, not map-verified) |
| Asquare Mall | ~1.68 km (aggregator-cited, not map-verified) |
Major Location Advantages
- Sector 50 is a centrally located, already-developed Noida sector, not dependent on future infrastructure to become livable.
- Two metro lines (Aqua Line and Blue Line) reportedly serve the immediate vicinity, a genuine rarity for a single micro-market in Noida.
- The sector sits on Golf Marg, a well-established internal arterial road rather than a peripheral or under-construction corridor.
- Being a mature society, immediate neighbourhood infrastructure (schools, hospitals, retail) is already operational rather than “planned” or “upcoming.”
What the Marketing Doesn’t Tell You
None of the specific landmark distances quoted by listing sites for this project have been verified with an independent map tool in this research pass, and at least one aggregator’s landmark data for this exact project appears to be templated content copied from a Delhi-based project rather than genuine Noida geodata. A buyer should independently map every claimed distance before relying on it. Separately, “Ready to Move” for an 18–20-year-old society means the buyer is evaluating two decades of wear, maintenance history, and RWA governance, not a fresh handover, and none of that operational condition is captured by any of the listing sites reviewed here.
Pricing & Configuration
| Configuration | Size (Sq. Ft.) | Starting Price (Current Resale) | All-In Estimated Cost |
|---|---|---|---|
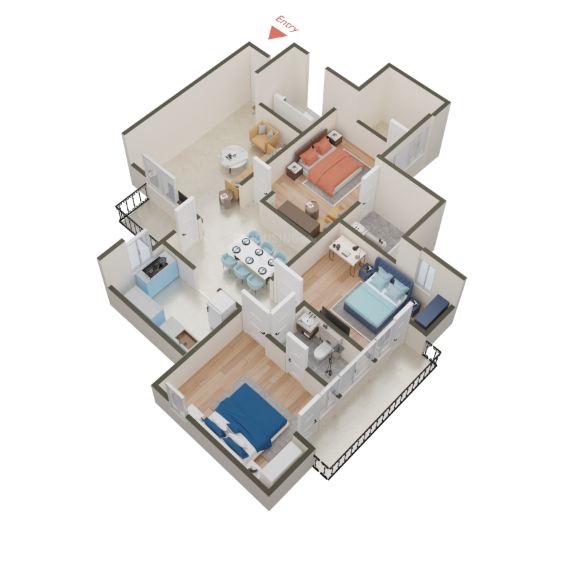
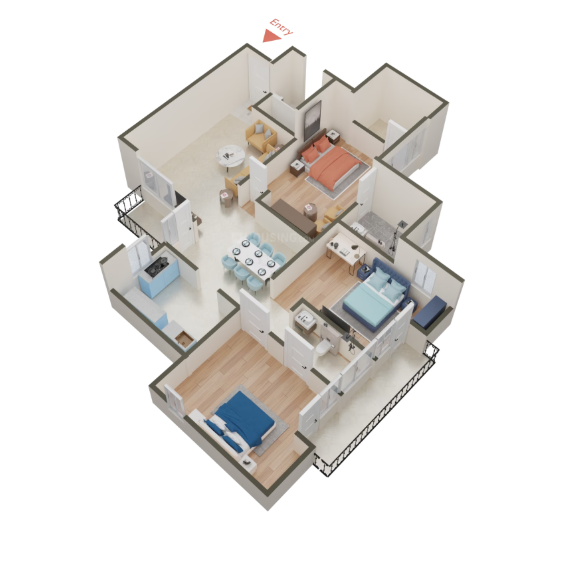
| 3 BHK | ~1,550–1,735 | ~₹2.72 crore | Not disclosed — resale registry/stamp duty costs apply on top; see below |
| 4 BHK | ~2,700–2,800 | ~₹4.85 crore | Not disclosed — resale registry/stamp duty costs apply on top; see below |
| “6 BHK” (unverified, likely combined/duplex unit) | Not disclosed | ~₹12 crore+ | Not disclosed |
Because Purvanchal Silver Estate is fully in the resale market, there is no active builder BSP, no construction-linked payment plan, and no official “price list” of the kind a new-launch review would document. Every transaction here is a private treaty between an existing owner and a buyer, cleared through registry and stamp duty rather than a builder collection schedule. That changes what a “Price Includes” and “Additional Charges” section can honestly say for this project. Those categories, standard for fresh bookings, do not map onto a 100%-resale project, so this review flags that gap explicitly rather than inventing figures to fill it.
Historical listing pages still show stale, launch-era pricing on some sites. Square Yards, for example, shows a static range of ₹1.26 crore to ₹2.27 crore (roughly ₹8,100/sq. ft.), and investormart.co.in shows “₹1.2 crore to ₹1.5 crore.” These figures are clearly outdated and should not be used to evaluate today’s market. The reliable current figure is the 99acres transaction-based data: average pricing moved from ₹15,950/sq. ft. to ₹16,400/sq. ft. in Q3 2025, a 2.82% quarter-on-quarter increase, with a marketplace median around ₹15,000/sq. ft.
Market benchmarking: Sector 50 as a whole trades in a range of roughly ₹11,750–16,700/sq. ft. per 99acres, with other trend trackers citing a somewhat lower average band of ₹12,710–12,780/sq. ft. Purvanchal Silver Estate’s current resale rate of ~₹15,000–16,400/sq. ft. sits at the upper-middle of this range: the project is trading roughly in line with, or modestly above, the sector average. This is not a red flag on valuation; it reflects a mature, established micro-market rather than a speculative premium.
Price Includes
Not applicable in the standard sense. Since every transaction is a resale, “what the price includes” is a matter of private negotiation between buyer and seller (fixtures, parking allotment, club membership status, if any) rather than a standardized builder inclusion list. This should be confirmed in writing with the specific seller for any unit under consideration.
Additional Charges
- Stamp duty and registration charges: governed by Uttar Pradesh’s current rates, calculated on the higher of the transaction value or the government circle rate (Sector 50 residential circle rate reported at ₹5,111/sq. ft. as of 2026, per HexaHome). Not disclosed by any project-specific source; must be calculated by a registry professional at the time of transaction.
- GST on resale: generally not applicable to resale of a completed, ready-to-move residential unit under current GST rules, but a buyer should confirm this with a tax advisor for their specific transaction.
- Society maintenance charges / IFMS: not disclosed anywhere found; must be obtained directly from the project’s RWA.
- Parking: allotment and any associated charge would be part of the private resale negotiation, not a published figure.
- Brokerage, if a channel partner or agent is involved in the resale: not disclosed, negotiable.
Payment Plan
Not applicable. There is no builder-linked construction-stage payment plan for a completed, resale-only project. Any purchase here is financed either through the buyer’s own funds or a resale-specific home loan, disbursed against registry documentation rather than construction milestones.
Builder Profile
| Particulars | Details |
|---|---|
| Legal Entity Name | Purvanchal Construction Works Private Limited (identified by RealEstateIndia.com as builder of record for this project) |
| CIN / Registration Number | U74899DL1994PTC061109 |
| Incorporation Date | 26 August 1994 |
| Registered Office | LSC A-7, 2nd Floor, Purvanchal Plaza, Mayur Vihar Phase-II, Delhi 110091 |
| Directors | Aftab Alam, Arshad Imam (per Zauba/ClearTax) |
| Claimed Experience | “30+ years,” “30+ projects completed,” “1000 happy clients” (per purvanchalconstruction.com — developer’s own claim, not independently verified) |
| Delivered Projects | Named delivered projects per ReraTracker: Purvanchal Silver Estate, Purvanchal Silver City I & II, Purvanchal Heights, Purvanchal Royal Park, Purvanchal Royal City Phase I. Broader claims of “50+ projects” and “18 total / 13 completed” appear across sources and are inconsistent with each other. |
| Clients Served | “1000 happy clients” (developer’s own claim, not independently verified) |
| Other Entities | Purvanchal Projects Private Limited (CIN U70102DL2010PTC200716, incorporated 25 March 2010, same registered office) — see narrative below for why this second entity is a material flag |
Two related but legally distinct companies surface across sources for the Purvanchal brand. Purvanchal Construction Works Private Limited was incorporated in 1994 and is the entity RealEstateIndia.com specifically credits with building Silver Estate. Purvanchal Projects Private Limited was incorporated only in 2010 (six to eleven years after Silver Estate’s own claimed 2005/2008 delivery), yet it is the entity that several aggregators and the group’s more recent marketing now treat as the flagship Purvanchal vehicle, and it is the entity whose leadership (Shah Alam) is publicly associated with the “Purvanchal” name today. A company cannot have delivered a project completed years before it was incorporated, so wherever aggregator material credits the newer entity with this specific project, that attribution is simply wrong. This is not a minor bookkeeping detail: for a buyer, knowing which legal entity actually stands behind a project’s original construction, and which entity would be a counterparty in any related legal matter today, is a real accountability question, and the group’s own public-facing materials do not answer it consistently.
Shah Alam, Chairman and Managing Director of Purvanchal Projects Private Limited, is a sitting Uttar Pradesh politician: MLA for Mubarakpur (Azamgarh) from 2012 to 2022 across shifting party affiliations, and MLC since May 2024. His own 2022 Election Commission affidavit discloses a pending criminal case: FIR No. 0234/2020 at P.S. Gomti Nagar, Lucknow, under IPC Sections 354A (sexual harassment), 354B (assault or criminal force with intent to disrobe), and 506 (criminal intimidation). Per the affidavit, no charges have been framed and there has been no conviction. The case remains pending. News coverage (Asianet Newsable, Swarajya) describes the underlying complaint as involving a woman employed by the company who alleged she was molested by Alam after being hired as deputy manager, with the complaint also separately alleging that Alam was involved in registering expensive flats at below-market rates, a financial-irregularity allegation that has not been adjudicated. This case predates and is unrelated to Silver Estate’s own construction, since Silver Estate was delivered before Purvanchal Projects Private Limited even existed. It is included here because it bears directly on the accountability and governance profile of the individual now most publicly identified with the Purvanchal name, which matters to any buyer weighing how a dispute with the group might be handled today.
Track record claims vary sharply depending on the source: the company’s own website claims “30+ years” and “30+ projects completed,” investormart.co.in states “18 total projects, 13 completed,” and ReraTracker cites “over 50 projects.” None of these figures could be reconciled against an independently audited or regulator-verified count in this research pass. Separately, the group’s active pipeline includes at least one documented delay: Purvanchal Royal City Phase II reportedly missed its original March 2023 completion deadline by roughly two years, per third-party sources. No independently audited consolidated financials or public credit rating for the group were found.
Risk Assessment — Positive Factors
- Sector 50 is a mature, centrally located Noida sector with functioning social infrastructure already in place, unlike newer peripheral projects still waiting on planned amenities.
- Two separate metro lines (Aqua Line and Blue Line) reportedly serve the immediate area, a genuine and unusual connectivity advantage for a single Noida micro-market.
- Current resale pricing (~₹15,000–16,400/sq. ft.) tracks within the established Sector 50 market band of ₹11,750–16,700/sq. ft. per 99acres. The project is not overpriced relative to its own locality.
- Sector 50 flats have shown consistent multi-year appreciation: 67.9% over three years and 102.9% over five years, per 99acres trend data. That points to durable locality demand rather than a speculative spike.
- Being fully delivered and 18–20 years old, the project carries none of the construction-delay or possession-slippage risk that applies to under-construction projects. The physical structure already exists and has a two-decade operating history.
- An active ApnaComplex page for the project suggests a functioning Resident Welfare Association and ongoing society management structure.
- No project-specific buyer complaints (as distinct from broader group/promoter issues) were found in this research pass.
Risk Assessment — Limitations
- RERA registration status is unverified and inconsistent across sources. Three different, mutually contradictory numbers appear on NoBroker, Square Yards, and gharpe.com, with the gharpe.com figure (“RAJ-123456789”) an evident placeholder for a Uttar Pradesh project. None could be confirmed on up-rera.in in this research pass.
- The legal entity behind the project is ambiguous. RealEstateIndia.com credits Purvanchal Construction Works Private Limited (incorporated 1994), while other aggregators associate the project with the Purvanchal brand now led through Purvanchal Projects Private Limited (incorporated 2010), an entity that could not have built a project delivered before it existed.
- The promoter most publicly associated with the current Purvanchal entity has a pending criminal case (FIR No. 0234/2020, IPC 354A/354B/506) per his own 2022 election affidavit, including a separately reported allegation involving below-market flat registration.
- Basic physical facts about the project disagree across every aggregator checked: land area is cited as either 4.00 or 4.87 acres, and tower count is variously reported as 1, 7, or 10, for the same 106-unit society. This level of disagreement on non-controversial facts suggests most listing data is stale or auto-scraped rather than verified.
- No original launch price or builder payment plan is documented anywhere, which is expected for a project this old but means a buyer has no baseline to judge how much resale prices have appreciated in absolute terms.
- Transaction volume is thin: only two government-registered resale sales totaling roughly ₹4 crore were found over the prior twelve months for a 106-unit society, which may indicate limited liquidity for a buyer who later needs to exit.
- No exact amenity specifications are disclosed for the clubhouse or any named facility, and after two decades of use, the current physical condition of amenities has not been documented by any source reviewed.
- Landmark distances circulated by aggregators are unverified against an independent map tool, and at least one source’s location data for this project appears templated from an unrelated Delhi project.
- The group’s active pipeline includes at least one documented delivery delay (Purvanchal Royal City Phase II, reportedly ~2 years past its original deadline), a relevant data point on the promoter group’s current execution discipline even though it does not implicate Silver Estate itself.
The Hidden Information Between the Lines
The most consequential finding in this research has little to do with Silver Estate’s bricks and mortar. It concerns who, precisely, stands behind the project as a legal and accountable entity today. Two companies share the Purvanchal name, registered office, and general brand identity, but they are separate legal persons with separate incorporation dates sixteen years apart. RealEstateIndia.com attributes this specific project to the older entity, Purvanchal Construction Works Private Limited, which predates the project’s own delivery and is therefore at least chronologically plausible as the actual builder. But the newer entity, Purvanchal Projects Private Limited, is the one whose leadership is publicly identified with the Purvanchal brand today, and various aggregators and track-record profiles casually credit it with this and other older projects it could not have physically built. For a buyer, this matters less as a historical curiosity and more as a live question: if a title, possession, or defect dispute arose today, which entity would actually be the counterparty, and does that entity have the assets and standing to answer for a project built under a different corporate shell decades ago?
The RERA data across aggregators tells a similar story of carelessness rather than active concealment, but the effect on a buyer is the same either way. A genuinely unregistered pre-RERA project and a project with sloppy, auto-generated aggregator listings look identical from the outside: both show inconsistent or fabricated-looking RERA numbers. The presence of an “AGT” (agent) prefix number being presented as a project registration, and a Rajasthan-format placeholder number appearing on a Uttar Pradesh listing, both point toward templated data entry rather than deliberate fraud. But a buyer cannot distinguish “the project is legitimately outside RERA’s scope” from “nobody has bothered to get this right” just by reading listing sites. That distinction can only be settled by a direct query to UP-RERA and the seller, which this research pass was not able to complete.
The promoter disclosure adds a different kind of hidden information, one that has less to do with the physical asset than with the character of accountability a buyer would be dealing with if anything went wrong. Shah Alam’s own election affidavit is a matter of public record, not rumor, and it discloses a pending case that, per news reporting, includes an allegation connected to irregular property registration practices at a company level. This predates and is unconnected to Silver Estate’s own construction, since Silver Estate was completed under a different, older entity. But it is directly relevant to anyone evaluating what recourse would look like if a dispute arose with “Purvanchal” as a brand today, since the group’s current public face carries this disclosed history.
Finally, the sheer degree of disagreement on basic, checkable facts (land area, tower count, even whether the project has one tower or ten) is itself a signal. These are not subjective marketing claims; they are physical facts that should be identical across every source describing the same building. That they are not suggests the secondary listing ecosystem around this project runs on outdated or copy-pasted data rather than verified records, which means a buyer should treat every number from these sources, including the ones not specifically flagged in this review, as a starting point for verification rather than a settled fact.
Questions to Consider Before Investing
- Can the seller or their agent produce a RERA registration number for this project that resolves to a matching project name and location on up-rera.in, or written confirmation that the project is exempt because it was completed before RERA’s applicability?
- Which legal entity (Purvanchal Construction Works Private Limited or Purvanchal Projects Private Limited) actually holds the original completion certificate, occupancy certificate, and land title documents for this project?
- Can the seller produce the original sale deed and completion/occupancy certificate for the specific unit under consideration, and do the entity names on those documents match?
- What is the actual, current land area and tower/block count for the society, confirmed against the RWA or municipal records rather than any listing aggregator?
- What are the current monthly maintenance charges, and is the RWA aware of any pending litigation, dues, or structural issues affecting the society?
- Is the specific unit’s title clear of encumbrance, and has a lawyer independently verified the chain of ownership back to the original allottee?
- What is the exact square footage and current operational condition of the clubhouse and other shared amenities, given the building is now 18–20 years old?
- Has the seller’s bank or the buyer’s proposed lender confirmed this project is loan-eligible, given the absence of a clearly verifiable RERA number?
- What stamp duty and registration costs apply to this specific transaction under current Uttar Pradesh rates, and who is responsible for paying which portion?
- Given the thin resale transaction volume (only two registered sales in the trailing twelve months per available data), what is the realistic timeline to resell this unit if the buyer needed to exit in three to five years?
- Is the buyer’s lawyer aware of, and has independently reviewed, the public record regarding Shah Alam’s pending criminal case and its relevance (if any) to Purvanchal Projects Private Limited’s current governance?
Who Should Consider This Project
- End-use buyers who specifically want a mature, established Noida location with existing (not future) social infrastructure and are comfortable buying a two-decade-old resale unit rather than new construction.
- Buyers who value proximity to two metro lines and are willing to independently verify exact distances rather than relying on listing-site figures.
- Investors with a long holding horizon who are comfortable with thin resale liquidity and do not need to exit quickly.
- Buyers who are prepared to fund the purchase primarily through personal funds or a resale-specific home loan and can tolerate additional lender scrutiny given the unresolved RERA question.
- Buyers who will commission an independent lawyer to verify title, entity, and RERA status before signing anything, rather than relying on aggregator listings.
Who Should Not Consider This Project
- Short-term investors looking for quick appreciation or a fast resale: trading volume here is thin, and exit timelines are uncertain.
- Buyers who are fully dependent on bank financing and cannot tolerate delays or rejections stemming from the unresolved RERA registration status.
- Buyers seeking a fresh, builder-warrantied unit with a construction-linked payment plan: none of that framework exists for this fully resale project.
- Buyers unwilling to independently verify basic facts (land area, tower count, legal entity, RERA number) that listing aggregators report inconsistently for this project.
- Risk-averse buyers who would be uncomfortable transacting with a group whose current public-facing leadership has a disclosed pending criminal case, regardless of its lack of direct connection to this specific project’s construction.
Honest Verdict
Purvanchal Silver Estate has real, verifiable strengths that should not be dismissed: it sits in a genuinely mature, well-located Noida sector with functioning infrastructure and unusually good metro access for a single micro-market, and its current resale pricing is fair relative to the broader Sector 50 market rather than inflated. As a place to live, the location fundamentals hold up to scrutiny.
The core problem is not the building. It is the paper trail around it. No source consulted in this research could produce a single, verifiable RERA number for this project; the Purvanchal brand’s corporate structure is split across two entities with a documented incorporation-date contradiction that aggregator sites gloss over; and the individual most publicly identified with the current flagship entity carries a disclosed, pending criminal case that touches on property-registration integrity. Individually, an older project lacking RERA registration is not unusual; plenty of legitimate pre-2016 societies fall outside its scope. But combined with the entity ambiguity and the promoter disclosure, the pattern here is one of persistently loose documentation and accountability across the group, not a single explainable gap.
A buyer should not walk away from this project on reputation alone, but should also not treat any aggregator’s numbers as settled fact. The concrete path forward is a direct RERA portal check, an independent lawyer’s title and entity verification, and a lender pre-check before any money changes hands. All three are inexpensive relative to a transaction of this size and would resolve most of the open questions this review could not close from public sources alone.
If UP-RERA confirms this project sits outside its mandatory registration window and the title chain checks out cleanly with the correct legal entity, this becomes a reasonably solid, fairly priced resale purchase in a strong location. Until that verification happens, treat every number on every listing site for this project as a lead to check, not a fact to rely on.
Disclaimer: This analysis is based on publicly available information gathered through independent research as of September 14, 2026. No financial advice is implied. Always consult a RERA-registered real estate agent and an independent property lawyer before making any real estate investment.